Finance rarely rejects a maintenance cost report because the number is too high. They reject it because it does not tie. The work orders total $412,000, the general ledger says $487,000, and nobody in the room can account for the difference without three days of invoice archaeology. Every facility team meets this moment the first time their spend gets taken seriously in a budget review — and the cause is almost never overspending. It is four separate cost streams captured in four separate places and reconciled by hand, once a year, under deadline. Start free with Oxmaint and close the gap between the work order and the ledger.
3-5x
Documented cost premium of reactive repair over the same job performed on a planned schedule
70-85%
Share of a reactive failure's true cost that sits outside the direct repair invoice and never reaches the maintenance line
2-5%
Typical annual maintenance spend as a share of replacement asset value, with strong performers holding under 3%
85-90%
Planned maintenance ratio targeted by best-practice programmes; below 70% the budget is predominantly firefighting
The Report Finance Wants Is a Reconciliation, Not a Total
A maintenance cost report has one job in a finance review: prove that the money the organisation spent on keeping assets running is fully accounted for, correctly classified, and attributable to something. A single total does none of that. The moment a controller compares your figure with the general ledger, the conversation stops being about maintenance strategy and becomes about data quality — and you lose the room. The reconciliation below is the shape of the problem in almost every facility organisation that has not yet centralised cost capture.
What the maintenance system reports
Closed work orders with logged labour hours
Parts issued from the storeroom at standard cost
Contractor jobs marked complete by the technician
PM tasks signed off on schedule
A number built from completed work
What the general ledger holds
Payroll at fully burdened cost, including overtime
Purchase orders received and invoiced, not issued
Accounts payable invoices with their own dates
Freight, equipment rental, permits and disposal fees
A number built from money leaving the business
The variance is rarely overspend. It is cost that was uncaptured, misdated across periods, or coded to the wrong account — three problems with three different fixes.
This is the difference between a maintenance report and a financial report. One describes activity; the other has to survive an audit. The good news is that closing the gap does not require an ERP project. It requires that every dollar of maintenance spend enters the same system at the moment the work happens, carrying the four attributes finance needs to place it: which asset, which cost category, which work type, and which cost centre. Book a demo to see cost capture configured against your chart of accounts.
Four Cost Streams, One Number
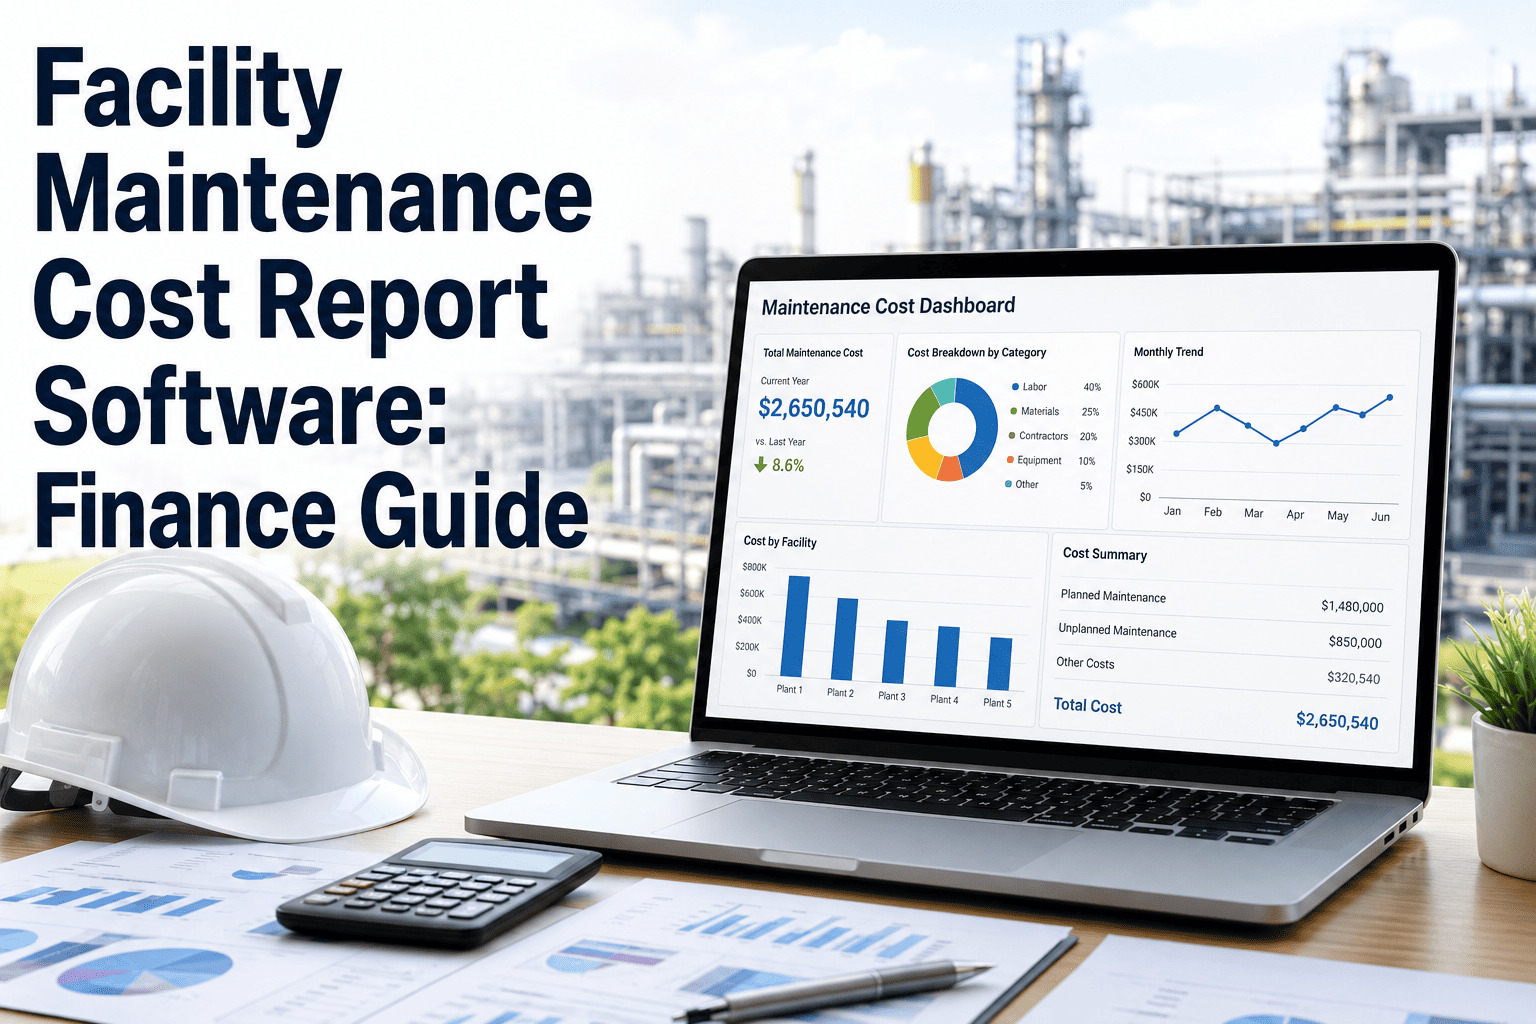
Facility maintenance spend arrives through four channels that rarely share a system. Internal labour flows through payroll. Parts flow through inventory and procurement. Contracted services flow through accounts payable. Everything else — rentals, freight, permits, waste disposal — flows through whatever card or requisition was nearest. The typical distribution below varies by portfolio and by how much work is outsourced, but the structure holds almost everywhere.
Typical composition of annual facility maintenance spend
Labour
Materials
Contracts
Internal labour, roughly 40-50%
Materials and spare parts, roughly 25-30%
Contracted services, roughly 20-30%
Rentals, freight, permits, disposal, roughly 5%
Internal labour
Hours must be logged against a work order and an asset, then valued at a burdened rate rather than base wage. Burden — payroll taxes, benefits, insurance, tools, non-productive time — commonly adds 25 to 40% on top of the hourly rate.
Capture rule: hours to the work order, rate from finance
Materials and spare parts
Cost belongs to the period the part was issued to a job, not the period it was purchased. Parts bought for stock are inventory; parts consumed are expense. Conflating the two makes maintenance spend spike in whichever month the storeroom restocked.
Capture rule: cost at issue, not at purchase
Contracted services
The largest single source of untied cost. An invoice approved in accounts payable with no work order reference cannot be attributed to an asset, a site, or a work type — so it lands in a general repairs account and disappears from every asset-level analysis you run afterwards.
Capture rule: no work order reference, no approval
Other direct costs
Equipment rental, expedited freight, permits, testing fees and disposal charges are individually small and collectively material. They are also the clearest evidence of reactive work, since planned jobs rarely need overnight freight or a weekend lift rental.
Capture rule: attach to the job that caused it
If the Invoice Has No Work Order, It Has No Story
Oxmaint captures labour, parts, contractor invoices and direct costs against the same work order — so every dollar arrives already attributed to an asset, a site and a cost code. Free to start, live in under 60 minutes.
Five Leaks That Make a Cost Report Untie
Each of these is ordinary, undramatic, and present in most facility organisations at once. Together they explain nearly every variance a controller will ask you to justify — and each has a fix that costs nothing but a decision about where data enters.
Understates labour by 25-40%
Hours valued at base wage
A technician logged at their hourly rate costs the business considerably more once taxes, benefits, insurance, vehicle and non-productive time are added. Reports built on base wage make in-house work look artificially cheap against contractor quotes — and they quietly bias every make-versus-buy decision that follows.
Shifts cost between periods
Parts expensed at purchase
When a bulk order hits the maintenance account on the day it is received, spend spikes in that month and looks suppressed in the months the parts are actually consumed. The annual total may be right while every monthly report is wrong, which is the version finance finds hardest to trust.
Breaks asset-level analysis
Contractor invoices with no asset reference
An approved invoice that names only a vendor and a site cannot be assigned to the chiller it was for. Run a top-twenty cost-consuming asset report on that data and the answer is wrong in the direction that matters most, because outsourced work concentrates on exactly the assets you most need to evaluate.
Distorts every accrual
Work completed in one period, invoiced in another
A job finished on 28 March and invoiced on 20 May belongs to March in any meaningful cost report. Without a completion date captured at source, finance either accrues on guesswork or lets the cost land in the wrong quarter, and the year-over-year trend becomes uninterpretable.
Misstates the P and L
Capital work coded as an expense
A component replacement that should be capitalised and depreciated instead lands entirely in the current year, overstating operating cost and understating the asset base. The mirror error, capitalising routine work, is the one auditors flag most often because it defers expense and flatters current earnings.
Hides the reactive premium
Work type recorded inconsistently
If emergency, corrective and preventive work are not classified at closure, the planned-versus-reactive cost split cannot be produced at all. That single split is the most persuasive number a facility leader can put in front of a CFO, and it is lost to a missing dropdown field.
Repair or Improvement: The Classification Test
The classification question decides whether a cost hits this year's operating result or gets capitalised and depreciated over decades — 39 years for commercial property under standard US depreciation rules. The tangible property regulations condense the test into three triggers applied to the unit of property: betterment, adaptation and restoration. If the work meets any one of them, it is capitalised. If it does not, it is a deductible repair. The examples below are the facility versions of each.
Swipe sideways to view the full table
| Test |
What triggers it |
Capitalise |
Expense as repair |
| Betterment |
Materially increases capacity, productivity, efficiency, strength or quality, or corrects a defect that existed at acquisition |
Upgrading electrical service to support new tenant load |
Replacing a worn component with a comparable equivalent |
| Adaptation |
Converts the property to a new or different use inconsistent with its original purpose |
Converting warehouse space into conditioned office use |
Reconfiguring within the same intended use |
| Restoration |
Replaces a major component or substantial structural part, or returns a deteriorated asset to working order |
Full roof replacement, or rebuilding an asset past its class life |
Patching a section of roof after storm damage |
| Routine maintenance safe harbour |
Work reasonably expected to recur more than once over the relevant period, ten years in the case of buildings |
Not applicable when the work is genuinely routine |
Recurring inspections, cleaning, testing and part replacement |
| De minimis safe harbour |
Per-item or per-invoice amounts below the elected threshold, with a written policy in place |
Amounts above the elected threshold |
Qualifying small purchases expensed on election |
Two practical notes. First, the same work can be classified differently depending on how the unit of property is defined, so the definition should be agreed with finance once and applied consistently rather than argued job by job. Second, whichever way a job is classified, the defence is documentation: scope, photographs, invoices and the completion record. A maintenance system that already holds all four turns a classification question into a lookup instead of a reconstruction. This page is general information, not tax advice — your controller or tax adviser owns the final call. Sign up free and build the documentation trail before you need it.
The Five Numbers Finance Actually Asks For
A cost report that answers these five questions ends the meeting. One that answers only the first invites a dozen follow-ups.
What did we spend, and on what
Total maintenance cost split by labour, materials, contracted services and other direct costs — then split again by site and by asset class. The split is the answer; the total is only the headline.
Reported monthly, not annually
Is that a lot, relative to what we own
Maintenance cost as a percentage of replacement asset value normalises spend against the current cost of replacing the asset base, letting a small site and a large one sit on the same curve.
Typical 2-5%, strong performance under 3%
How does it compare per square foot
Cost per square foot is the language property and real estate teams already use for every other line item. It travels badly across building types, so compare within a portfolio and within a use class only.
Compare like for like, or not at all
How much of it was avoidable
The planned versus reactive cost split, with the reactive share priced at its real multiple. This is the number that converts a maintenance budget request into an investment case a CFO can evaluate.
Target above 85% planned
Why does it differ from budget
Variance with a cause attached to each line: an asset failure, a scope change, a rate increase, a deferred project. Variance without explanation reads as loss of control even when the spend was correct.
Explain every line above threshold
What is it likely to be next year
A forecast built from PM schedules, contract renewals, asset age and observed failure history — not last year's figure plus a percentage. This is where a maintenance system becomes a planning tool.
Bottom-up beats indexed
One caution worth carrying into the meeting: a falling maintenance cost ratio is not automatically good news. A number that improves because critical work was deferred has moved cost into a future period rather than removing it, and the trend will reverse violently. Best practice guidance is explicit on this point — the ratio should never be read alone, and it should always be read alongside planned maintenance percentage and backlog. Book a demo to see cost and reliability metrics reported together.
A Five-Day Close Instead of a Three-Week Scramble
When capture happens at the point of work, the reporting cycle stops being a data collection exercise and becomes a review.
Day 1
Close the work
Every job completed in the period is closed with hours, parts, work type and completion date recorded. Open jobs with committed cost become the accrual list.
Day 2
Match the invoices
Contractor invoices are matched to their work orders. Anything unmatched is chased while the job is still recent enough for someone to remember it.
Day 3
Value and classify
Labour is valued at burdened rates, parts at issue cost, and any capital-candidate jobs are flagged for the classification review rather than assumed.
Day 4
Reconcile to the ledger
Compare the system total against the account balances. Investigate differences by category, which turns a single unexplained variance into three small ones.
Day 5
Explain and issue
Attach a cause to every material variance, publish the splits and the ratios, and carry the open backlog forward as a stated commitment rather than a surprise.
Stop Rebuilding Last Quarter's Spend From Email Threads
Labour, parts, contractor invoices and direct costs captured at the work order. Asset, site, work type and cost code attached automatically. Exportable in the format your controller already uses.
Frequently Asked Questions
Does Oxmaint replace our accounting system?
How do we get burdened labour rates into the report?
Finance supplies the burdened rate per trade or per technician, and it is applied to logged hours automatically. Technicians keep recording time as normal; the valuation happens behind the report rather than in a spreadsheet afterwards.
Sign up free and configure rates in minutes.
Can it split capital work from operating expense?
Yes. Jobs can be flagged as capital candidates at creation or at closure and reported separately, with scope, photos and invoices attached as supporting evidence. The classification decision stays with finance; the documentation comes ready-made.
Book a demo to walk through a capital review.
What about contractor invoices that arrive weeks after the job?
The work order holds the completion date and the committed cost, so the expense is recognised in the right period and the invoice matches against it when it lands. Unmatched invoices surface as an exception list rather than a year-end mystery.
Start free and see the exception list on your own data.
How long before we can produce a report finance accepts?
Asset registry and cost capture activate within days, with a full reporting cycle typically complete after one or two closes. The first month is a baseline; the second is where the variances start explaining themselves.
Book a demo to plan a multi-site rollout.
The Budget Conversation Goes Better When the Numbers Tie
Four cost streams, one work order, one report your controller can sign off. Capture at the job, attribute to the asset, explain every variance. Free to start, no implementation fee.